THE PREDICTION ECONOMY
Moving into the third level of value creation
menu
INDEPENDENT RESEARCH · THE THIRD LEVEL OF VALUE CREATION

THE PREDICTION ECONOMY

Part 1 · , July 29, 2026
INTRO: ROTHSCHILDS PIGEONS

june 1815, and all of london is waiting on waterloo.

napoleon against wellington - the battle that will decide the fate of europe.

and the outcome will decide the price of every bond in the market.

but one family has spent years preparing for exactly this moment.

the rothschilds have built the fastest private courier network in europe - riders, boats, and, so the legend goes, carrier pigeons.

napoleon lost.

nathan rothschild knew a full day before the government did.

and he traded on it. he made roughly £600 million in today’s terms by 1817, from this single position.

the edge was never capital. it was seeing first. the couriers were not a messaging business. they were sensors, pointed at a continent, owned by the one family that understood what a day’s head start was worth.

this document is about the courier networks being built right now - and about the people building them, who mostly aren’t saying so.

intelligence is only worth what it can see

i tracked the last fifteen acquisitions across the most sophisticated serial acquirers of vertical software. constellation software, openai, beacon - deal after deal, the same shape: buy the layer that serves a market, and you see that market move before anyone else does - every shift in the economy shows up in the books of the people who serve it, months before it shows up anywhere else.

they are buying the pigeons.

because the moat is moving. great tech is no longer the advantage - software is commoditizing, and value migrates up a layer each era. the SaaS era of the 2020s - sell the tool - is undisputedly over: valuations have dropped, and companies are building proprietary stacks instead of renting. the current wave - service-as-software - runs the tool and sells the outcome, and the AI rollups belong to it too: owning more of the value chain is just a different way of capturing the same work. but extrapolate the trendline to where it terminates: models become a utility, operations become a commodity, and distribution - the network that gives intelligence its eyes - becomes the last layer standing. competition doesn’t stop. it moves to the only axis left - who sees the market first.

i call that phase the “prediction economy”: the point at which the winners in vertical markets are no longer the ones who automate the work, but the ones who see the market through the work - whose margins are shrinking, who is about to lay off, where the breaches are hitting. and the advantage compounds in sequence: seeing first becomes a selection advantage, then a pricing advantage, then a timing advantage - until, in illiquid markets, it converts into a compounding position, and finally into a terminal asset: you become the reference layer the market prices itself against.

the player becomes the house.

and the position, once built, cannot be rebuilt. because the advantage is not capital, talent, or software, all of which money can buy. it is accumulated history, which money cannot. a market panel that started recording in 2026 can never be caught by one that starts in 2028. history is the one thing money can’t compress.

the rothschild edge, industrialized.

Pablo Picasso, Le pigeon aux petits pois, 1911
Le pigeon aux petits pois, Picasso

CHAPTER I

from software to infrastructure

the main idea: in the last months software has become a commodity. software was priced as SaaS. that changed because now software is easier to build than ever. in the latest months operators started “service as software” to capture higher margins. at some point all legacy companies will have implemented the same automation, which will lead to price drops. a new layer of value creation will emerge: anticipation of market changes, based on what software companies know best, generating users and tracking their behavior. software companies will go as far as to not monetize the user anymore to not slow down user growth. what the biggest software players and labs are already doing is buying access to different target groups, through podcast acquisitions, through newsletter acquisitions, through buying software tools, sunsetting the software and only using the users.

three things changed in the last eighteen months. AI collapsed the rebuild cost. the buyers moved up the stack. and capital piled up faster than credible vehicles to absorb it. to see where value is going, start with where it’s been.

what follows now are the three layers of pricing that software moves through. layer one: sell the tool, capture 2-5%. layer two: sell the outcome, capture 30-60%. layer three: own the informational advantage your distribution creates, and price it to buyers who were never your customers in the first place. the first two exist today. both are already priced. both terminate. the third is what the rest of this document is about.

level one: sell the tool.

classical SaaS. subscription pricing on software the customer runs themselves. the honest math on the capture: 2 to 5% of the value created. if a software tool saves a sales org 30% of their time and closes 20% more deals, the customer keeps 95% of the value. you get the subscription.

that was fine when software was expensive to build and hard to replace. neither is true anymore.

in june 2025, Wix paid $80 million in cash for Base44. an app-building platform six months old, built by one man, Maor Shlomo, with no outside funding and fewer than ten employees. one person, half a year, eighty million. a competitor with a coding agent replicates most SaaS in weeks. the moat classical software rested on, the thing that made a five-year subscription defensible, is now a rounding error on someone else’s development timeline.

AI collapsed the rebuild cost. LTVs are finite. code depreciates.

selling the tool is a shrinking share of a shrinking pie. this isn’t the answer to what comes next. it’s the answer everyone is trying to escape.

level two: sell the outcome.

same software. but you don’t sell it. you run it yourself and sell the result.

AI-native law firms replace paralegals and associates with agents and sell filings directly to end clients. Crosby does this. AI-native insurance carriers underwrite and issue policies in minutes. Corgi does this, full-stack, licensed, $2.6B valuation eighteen months after founding. AI-native accounting practices run 90% automated and sell filed returns.

capture jumps from 2-5% to 30-60%. not because the software got better. because the customer can no longer comparison-shop you against another vendor. they’d have to replace the whole function.

that’s pure service as software. one operation. built AI-native from day one. sold directly to end clients.

Sam Lessin’s answer takes it further. use software to run real businesses better, then buy them and keep the entire uplift. Metropolis is the flagship. it didn’t sell parking software. it raised a $1.8 billion package and took SP+ private at a 52% premium on a century-old public company: $1.5 billion including debt, the largest venture-backed M&A deal of 2024. the prize: the biggest parking operator in north america. four thousand locations, twenty thousand employees, four billion dollars a year in payments flowing through one company’s computer vision. Metropolis captured the whole delta. and the thesis has skin in it. Slow Ventures, Lessin’s own firm, is in the financing.

this is the strongest existing answer in circulation. it has serious backing. Slow Ventures has built a thesis around it. operator-founders are structuring vehicles that assume it. and it’s coherent. the value creation is real, the capture structure is defensible, and the transaction evidence exists.

Lessin’s argument, stated fairly: classical SaaS captures a small slice of the value it creates. AI collapses the moat around software itself. the winning move is to stop selling the tool, run the operation, and own the business the operation transforms. equity captures what fees couldn’t. ownership is what comes after SaaS.

the AI rollup wave is this argument in execution.

it’s leveraged service as software. instead of building one operation from scratch, you buy operations that already have customers and run them AI-native. same value capture logic. bigger surface area.

Crescendo acquired PartnerHero and is rolling out AI customer service to its 200 customers, taking gross margins to 60-65%. Long Lake has acquired 18 businesses with 25-30% productivity gains in HOA management and a 10x increase in new-customer pipeline. Dwelly acquired six property-management agencies and doubled EBITDA margins where the tech is fully deployed. Titan acquired RFA and cut user onboarding from weeks to minutes.

the mechanics are subtler than the discourse admits.

the customer isn’t paying more. the operator delivers at a fraction of the cost. the delta is the margin. the AI has to be invisible enough that the customer doesn’t churn and effective enough to double free cash flow in eighteen months.

the band is 30-70% automation. below 30%, you can’t underwrite the value creation. above 70%, you’re buying expensive headcount you’re about to automate away. between 30 and 70%, you’re buying real operational substance that AI can meaningfully transform but not replace. CPAs. MSPs. property managers. call centers. this is the band where rollups make sense.

the multiple only re-rates if the transformation is real. Constellation, TransDigm, Danaher trade at 20-25x EBITDA because they demonstrably improve the companies they buy. aggregate assets without transformation and you deserve a PE multiple. genuinely double free cash flow through AI across a portfolio and you can argue for something closer to a software multiple.

what holds customers after acquisition is not the relationship. in order: processes get better and issues resolve faster. the seniority and knowledge of the combined group. greater options and support. and only fourth, the existing relationship. outcome improvement is the moat.

level two works. i’ve argued it against its critics, transaction data in hand.

but ownership is a capture structure. not a level.

buying the company you operate better changes how much of the value you keep. it doesn’t change what the value is. you are still monetizing the operation. equity instead of fees is a payment structure, not a category shift. a level, properly defined, monetizes a different object entirely.

and the defensibility question doesn’t go away when you own the operation. an operation is replicable. not in weeks like a tool. in years, by a funded competitor buying into the same band of the same vertical. every Metropolis has a competitor two years behind it with the same acquisition thesis and a cheaper cost of capital. the proof is already on this page: Long Lake and Dwelly are the same thesis in the same band. two geographies, funded independently. ownership is a stronger position than tool-selling. it’s not a permanent one.

run the sequence forward the way you’d extrapolate any trendline.

level one goes to free. the tool already functions best as an entry point, a customer-acquisition cost. HubSpot proved the endgame a decade ago. the free CRM was never the product, it was the acquisition machine. now reread the purchase log above: the same company is skipping the tool entirely and buying the audiences outright.

level two goes to commodity. every credible operator will have the automation, because the automation is for sale.

ownership captures more of level two while it lasts. it doesn’t extend how long level two lasts. software stops being a product and becomes infrastructure. everyone has it. nobody wins on it.

so the smartest buyers stopped buying software a while ago. the tape shows what they’re buying instead.

reach, then sight.

april 2026. OpenAI makes the first media acquisition in its history: TBPN, a daily tech talk show. fifty-eight thousand youtube subscribers at signing. terms undisclosed, reported at hundreds of millions. run the math per subscriber and the deal is absurd. run it per room reached and it’s cheap: TBPN is where the industry talks to itself, and OpenAI bought a permanent seat. the company whose models everyone rents concluded the scarce asset wasn’t the model. it was the channel.

HubSpot is running the same migration as a series. The Hustle in 2021. a newsletter, an audience. Starter Story in february 2026. another newsletter, another audience.

that’s reach. distribution by volume. rooms entered.

and the serial acquirers went a level higher still.

Constellation Software, roughly a hundred vertical acquisitions a year, the most disciplined buyer in the game, bought Keypoint Intelligence in may 2026. not a tool that operates in the digital-imaging vertical: the benchmark authority the vertical measures itself against.

Beacon Software deserves a longer look, because it is the Constellation model being rebuilt in real time. AI-native, venture-funded, and in a hurry. founded in Toronto in 2024 by Nilam Ganenthiran, Instacart’s former president, and Divyahans Gupta, ex-Sequoia, ex-Databricks. roughly thirty acquisitions in two years. lately one a week, sixty days from open to close. more than half a billion dollars across three rounds in twenty months, the latest this june, at a reported $1.4 billion valuation. General Catalyst, D1, Lightspeed. the sharpest venture money is no longer only funding builders of vertical software. it is funding a buyer. and the structure is permanent. Beacon holds forever, the anti-private-equity pitch. which is precisely the structure for which an accumulated position compounds instead of expiring at fund term.

in march, Beacon paid eight figures for RealEstateAPI: bootstrapped, no institutional capital, property data on 150 million american homes, serving three hundred companies. not a tool that operates in a market. the data layer under one.

and Beacon doesn’t hide the logic. its pitch to founders promises domain data most teams can’t reach. sell us your company, gain access to datasets you couldn’t build alone. its founder’s frame, stated in public: as AI turns competence into a commodity, the scarce asset left is trust. trust is distribution by its human name. a channel already open, already answered. and the market Beacon is pointed at is, by its own count, the underserved industries that make up more than half of US GDP.

read that sequence twice. the newest, fastest buyer of vertical software is telling sellers that the moat is the relationship and the prize is the data behind it. what took Constellation three decades of discipline to assemble, venture capital is now trying to manufacture inside a single fund cycle. the class of buyer for these instruments is being created at venture speed, right now.

the buyer of the software is advertising the data.

that’s sight. not just rooms entered. rooms understood.

and it’s not new. the tape is longer than the AI cycle.

the tape.

Monsanto paid roughly a billion dollars for Climate Corp in 2013, to see every field it sold into. ICE paid roughly twelve billion for Black Knight in 2023, to see the life of every american mortgage. Mastercard paid $2.65 billion for Recorded Future in 2024, to see threats move before they land. Moody’s paid two billion for RMS in 2021, to own the catastrophe baselines the insurance market prices itself against.

and Verisk. an insurer data consortium that grew into a listed company. the terminal form: the panel outlived every tool around it.

the trendline compresses. two decades of tools. five years of reach. now sight, with deals landing months apart. the intervals shorten. the shelf doesn’t restock. most verticals never built a Keypoint. behind most of the economy there is nothing to acquire.

the tape terminates in a shortage. and a shortage is why the capital is already stacking behind the few vehicles that can absorb it.

the capital is already there.

General Catalyst committed $1.5 billion of a single fund to AI rollups. Thrive is raising a permanent vehicle north of a billion for the same job. Beacon, two years old, has raised over half a billion across three rounds. Metropolis, after the $1.8 billion package that funded SP+, took another $1.6 billion in november 2025. J.P. Morgan arranging a billion-dollar term loan for a parking startup.

the pressure is real, and it’s on the value-capture side. capital piled up faster than credible vehicles to absorb it.

Peter Thiel wrote in 2014: “superior distribution alone can create a monopoly, even without a better product. a better product alone cannot.”

the capital knows. the buyers know. the question is what they’re buying toward. and the answer is already visible in the purchases above.

what remains scarce?

the tools are free. the operations are commodity. ownership terminates at the value of the work being done.

what remains scarce when all three are true is what the buyers on this page are already moving toward. not the software. not the operation. the informational advantage the distribution creates. who is churning, who is growing, whose margins are compressing, where the breaches are landing. the layer that sees the market through the work.

the smartest operators will stop monetizing the user entirely, because friction slows distribution, and distribution is the sensor grid. the user isn’t the customer. the user is the instrument.

that is the third level. chapter II names it precisely.
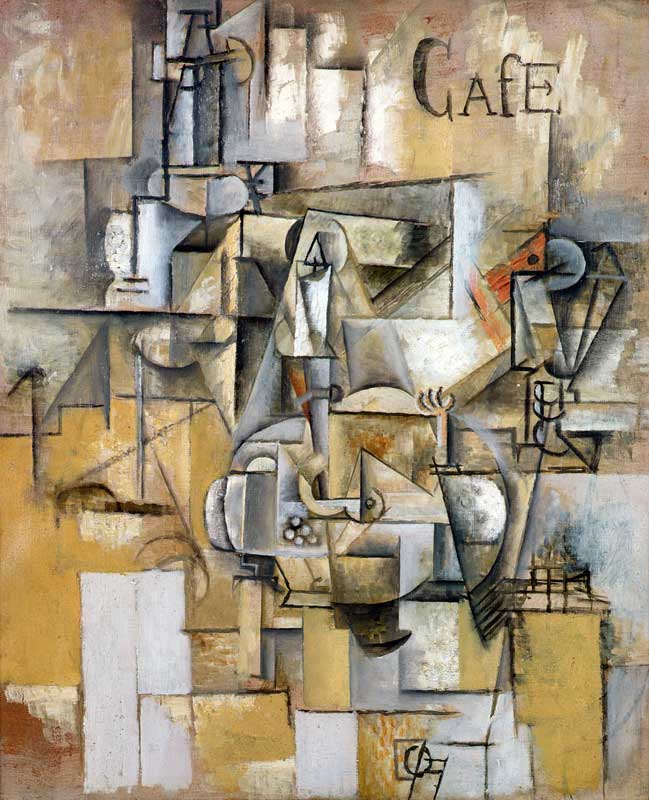
next: II. the third level of value extraction →

CHAPTER II

the third level of value extraction

the main idea: software went through three pricing eras. first, sell the tool. second, sell the outcome. third, own the informational advantage your distribution creates. the first two are already commoditizing. the third monetizes a different object entirely: not the work, but what the work lets you see. who is churning, who is growing, where margins compress, months before it shows up anywhere else. two paths follow. sell that signal to a third party who pays. or deploy it against your own balance sheet and compound. the tool depreciates in weeks. the operation replicates in years. the panel is time-locked.

there is a cleaning company in new york i keep thinking about.

they clean your house for free. no subscription. no upsell. no invoice. the twist is that every cleaner wears a camera. every session is filmed. every corner, every surface, every motion.

their bet: in five years, humanoid robots will do household cleaning. and the company that owns the most video of humans actually cleaning real homes will train the best robots. the robotics companies will pay more for that data than any household would ever pay for the cleaning.

so they don’t monetize the cleaning. they monetize the data.

the cleaner is not the product. the video of the cleaner is. and you are not the customer. the robotics company in three years is.

they play free with everyone whose money isn’t the real money.

the inversion.

that parable marks a transition between monetization eras.

the 2020s were software as a service. sell the tool. the current wave is service as software. run the tool yourself, sell the outcome. the emerging model, still non-obvious to most operators, is own the informational advantage your distribution creates. build reach through a network, and monetize what the reach lets you see rather than what the network does.

level three: own the information advantage your reach creates.

when you hold the platform layer across a meaningful share of a vertical’s connective tissue, you stop being a software business in any meaningful sense. you are watching an entire end-customer economy evolve in near-real time. which sectors are heating up. where margins compress. where cash cycles stretch. months before any of it appears in a published statistic.

the object of level three is not the software. not the operation. not even the customer relationship. it is the aggregate anonymized signal your reach generates about the economy behind it.

the tool and the operation exist to feed it. this is the inversion most operators miss. in level one and level two the software is the product. in level three the software is the sensor and the panel is the product.

the working precedent exists. Penny Lane, in france, built its actual moat not as bookkeeping software but as access to SME financial data through tax advisors. the software was the door. the reach was the asset.

but a claim like that has to earn its mechanism. what actually creates an economy-scale signal, at a velocity someone can execute? one kind of firm in one specific position. chapter III names it.

the ladder.

before naming the two paths, name what the telemetry actually gives you. the answer has five rungs, and they build in sequence.

first rung: selection. which firm to buy, which market to enter, which node to prioritize. real, but weakest. selection without the next rungs is just a better watchlist.

second rung: pricing. not just which firm to buy. what it’s worth before anyone else can compute it. you know the practice’s true cash trajectory while the seller’s own bank is reading stale statements. every transaction you enter is systematically mispriced in your favor. the blind acquirer and you can bid on the same asset. you’re not outbidding him. you’re out-knowing the price.

third rung: timing. not which, not what it’s worth. when. the telemetry tells you which market becomes automatable in three years, which succession wave forms in eighteen months. you enter before the re-rating, before the chorus. selection tells you where to stand. timing tells you when the ground moves.

fourth rung: position. in liquid markets, rungs one through three decay. knowledge arbitrages away. in the markets this thesis targets, illiquid, private, small, knowledge converts to ownership before it can leak, and then the loop closes. signal, allocation, network, sharper signal. the advantage stops being something you spend and becomes something that compounds. that is the difference between alpha and an asset.

fifth rung: reference. at sufficient density and calibration, something qualitative happens. you stop extracting edge from the market and the market starts coordinating through you. banks price SME credit against your feed. insurers set premiums against your baselines. acquirers value practices against your comps. at that point your information isn’t an advantage anymore. advantages decay. it’s infrastructure. and infrastructure doesn’t earn alpha. it earns rent.

the ladder in one line each: selection tells you which. pricing tells you what it’s worth. timing tells you when. position makes it compound. reference makes it permanent.

the player becomes the house.

and there is a sixth rung, the one worth stating carefully. at density, in small markets, the arrow reverses. you stop predicting the futures and start scheduling them. you don’t forecast the succession wave. you trigger it, three nodes at a time, matching aging books to young advisors through your own network, and then watch the effects propagate through your own sensor. foresight becomes agency. the market’s future becomes partially yours to write.

that is what the telemetry layer gives you. the question is what you do with it. two paths open.

path one: sell the signal.

mid-term. anonymized, aggregated, structured for the third party who cannot build it themselves. hedge funds paying for pre-print macro signal. banks pricing SME credit exposure against a real-time feed nobody else has. insurers pricing small business risk against sector-level cash flow patterns. macro desks paying for structural shift indicators months ahead of published statistics.

this is the cleaning company parable, generalized. the tax advisor doesn’t pay. the entrepreneur doesn’t pay. the network rides for free. the third party who benefits from access to what the network generates covers the entire operation.

the ceiling is set by what data buyers pay per year. the exit has a proven shape. the sellable form of a signal layer already has a name and a price. Keypoint Intelligence. RealEstateAPI. the benchmark business with paying subscribers. bounded outcome. clean, defensible, predictable revenue.

path two: deploy the signal.

long-term. keep the panel internal. use it to make your own allocation decisions. which sub-verticals to build into next. which regional practices are quietly consolidating clients, ready to be bought at multiples the market hasn’t priced. which SMBs are growing structurally and worth expanding your network toward first. which owners are approaching succession before anyone else has made the call.

the panel becomes an origination engine for your own capital. every insight sharpens the next allocation. every allocation tightens the network. every new node sharpens the panel.

signal, allocation, network, signal.

no exotic technology required. just an information edge, applied to your own balance sheet, compounding. the ceiling is set by the size of the vertical you’re building through, not by what a hedge fund will pay for a data feed. bigger upside. bigger execution risk. requires capital you may not have and patience the board may not want.

why both paths prove the same thing.

both prove that level three monetizes a different object than level two. path one monetizes third-party access to what your reach sees. path two monetizes your own capital compounded against what your reach sees. neither monetizes the operation. both monetize the information advantage the operation happens to generate as a byproduct.

that is what makes level three a level. not a capture structure applied to level two. a different object entirely.

the alphago objection.

the third level rests on a bet: that data gathered from the world stays valuable in a world of abundant intelligence. my own hesitation with the entire monetize-the-third-party model lived exactly here. and there is a famous pattern that feeds the hesitation, so it deserves the full telling rather than a footnote.

go is an ancient board game. black and white stones, simple rules, more possible positions than atoms in the universe. for decades the consensus was that computers would never beat humans at it. too intuitive, too creative. in 2016, DeepMind’s AlphaGo played Lee Sedol, the world champion. best-of-five, watched by millions. AlphaGo won 4-1.

but the part that matters for this thesis is how it was trained. two phases. phase one: it studied millions of human expert games and learned to imitate the best players. that got it to strong-human level. good, not historic. phase two: it played against itself. millions of games, no human data at all, learning from every win and loss. self-play. that is what made it superhuman, producing moves no human had conceived in 2,500 years of the game.

then the punchline. a year later, DeepMind built AlphaZero and skipped the human games entirely. pure self-play from zero. it crushed the original AlphaGo.

so here is the pattern, stated plainly: human data gets you to human level. self-play gets past it. and eventually the human data isn’t needed at all. run that pattern against the cleaning-company parable and every “sell human data to the labs” play in this document, and the warning writes itself. the window is real. but history says: it closes.

or does it?

self-play worked because go is a closed world. perfect information. the board simulates itself. the economy is not a board. the economy must be observed. no amount of self-play generates the fact that layoffs started in freight forwarding last tuesday. intelligence is not the same as knowledge of the present. a superintelligence in a datacenter is still blind. it cannot deduce this quarter’s margins in austrian dental practices from first principles. someone has to measure the world. compute cannot conjure ground truth.

so concede the alphago point where it applies. and it does apply. data that teaches skills is a wasting asset. the labs will eventually self-play their way past most of it, and any thesis priced on selling skill-data forever is priced wrong. the cleaning company’s window is real and it closes.

and notice what survives the concession. in a world of abundant intelligence, the scarce input flips from thinking to seeing. models commoditize. sensors don’t. the rothschild edge survives even AGI. it may be the only edge that gets more valuable under it, because faster actors extract more from the same time advantage. the pigeons matter more when everyone can think at the speed of light and nobody can see past their own walls.

the defensibility hierarchy.

three levels. three sentences.

the tool depreciates. AI rebuilds it in weeks.

the operation scales. a funded competitor replicates it in years.

the panel is time-locked. nobody can replicate it without replicating your entire network history. and history is the one thing money can’t compress.

only one layer of one asset in the stack gets more defensible with time. everything below it exists, in the end, to feed it.

what remains is the mechanism.

how a network actually generates economy-scale signal. legally. at a velocity someone can execute. through what specific structural position.

not scraping. not surveillance. not buying data.

one kind of firm in one specific position. everyone has been mispricing them.

chapter III names it.

next: III. the multiplier →

CHAPTER III

the multiplier

the main idea: a multiplier is a firm that serves firms. one tax advisor is platform reach into the bookkeeping reality of dozens to hundreds of SMEs. 1,500 nodes is one hop to a national SMB economy. the same arithmetic runs in insurance brokerage and property management. run the numbers on any real market and two laws fall out. organic pace builds footholds, not networks. the multiplier can never be the one paying.

a multiplier is a firm whose customers are themselves firms.

tax advisors serve dozens to hundreds of small businesses.

insurance brokers sit in front of dozens of policy-holding entities.

managed service providers run the IT reality of a portfolio of SMEs.

property managers hold the operational layer of many owners’ buildings.

the arithmetic is the entire point.

one tax advisor is one customer. but behind one tax advisor sits the bookkeeping reality of every SME they serve. behind 1,500 advisors sits a meaningful share of a country’s economy. real-time financial data. bottom-up macro signals. industry-level benchmarks. cash-flow patterns across the entire small-business economy.

you don’t build reach to the network. you build reach through it. one hop through a partner the end customer already trusts.

reach to end customers adds. reach through multipliers compounds.

every new end customer is one more customer. every new multiplier node is a window onto dozens more firms. and the aggregate assembles into something no individual participant possesses. the pattern-level movement of a whole market.

this is what separates the multiplier position from every adjacent-sounding thing. audiences. user bases. mailing lists.

the selection rule.

fragmentation × end-customer leverage.

fragmentation matters because no incumbent controls the layer. end-customer leverage matters because every node is a multiplier onto many more.

verticals that pass the test: tax advisors. insurance brokers. MSPs. property managers. mortgage brokers. benefits consultancies. accounting firms. freight forwarders.

verticals that fail: direct-to-consumer services. verticals with one incumbent controlling the layer. verticals where the multiplier is only nominal and the actual buying decision sits at end-customer level.

two laws.

the real numbers in these markets expose two laws that the abstractions hide.

law one: organic pace builds footholds, not networks.

in any multiplier vertical, the market is large and fragmented. austria alone has 3,000 tax advisors. germany has 46,000 insurance brokers. the US has 50,000 property management firms handling 20+ million doors.

organic onboarding cannot reach density in these markets. at aggressive organic pace, a platform reaches low single-digit penetration in two years. that is a foothold, not a network. and no acquirer pays for a foothold. acquirers pay for meaningful distribution: the majority of a market.

the implication is structural: any operator building toward the multiplier position must solve for velocity, not product depth.

law two: the multiplier can never be the one paying.

the moment the multiplier has to pay, they slow down. they compare. they negotiate. they wait for budget approval. they ask their partners. they miss your emails.

the whole flywheel jams.

velocity is the economics. payment is friction.

so the law follows.

the multiplier is not your customer. the multiplier is your distribution. the multiplier rides for free. a third party pays.

what sits behind the verticals.

the market sizes matter because of what sits behind them.

behind each tax advisor: the bookkeeping reality of every SME they serve. cash flow, margin trends, sector composition, employment patterns. behind 1,500 advisors in a national market: a real-time telemetry of the SMB economy.

behind each insurance broker: dozens to hundreds of SME policy holders. cyber. D&O. professional liability. property. behind 46,000 brokers: the underwriting reality of a national SME insurance market.

behind each property manager: hundreds of units, thousands of tenants, hundreds of owners. behind 50,000 firms: real-time patterns on maintenance backlogs, vacancy trends, rent behavior, insurance claim frequency, and owner distress across a national residential real estate market.

the buyer for this signal isn’t hypothetical. Beacon already paid eight figures for RealEstateAPI, a bootstrapped property-data business with 300+ paying customers. the productized version of a property-manager panel has a market that has already cleared price.

the harper question.

i argued in my substack piece on Emergence Capital that the automation spectrum determines whether a vertical is a rollup, an organic play, or something else. below 30%, the AI transformation isn’t deep enough. above 70%, you’re buying headcount you’re about to automate away. the band between 30 and 70% is where rollups make sense.

Harper Insure runs above 80%. they replaced the broker entirely. inbound is enough at their scale. that is the disintermediation case, not the multiplier case.

the multiplier play in insurance is not Harper. it is the 46,000 legacy brokers who still hold the SME market Harper does not touch. the top segment gets disintermediated. the bottom segment stays multiplier-mediated. the multiplier position is the second one.

why now.

two conditions make these markets uniquely available.

the ownership layer is aging. most tax advisor owners are past 55. most insurance broker owners are past 55. property management is slightly younger but the retirement wave is forming. every year the market softens further.

and the automation grade in all three verticals sits exactly where the third-level play requires. high enough that AI can meaningfully transform the workflow. not so high that the multiplier disappears. the multiplier stays. the workflow improves. the reach compounds.

one hop to an economy.

that is what the multiplier position is. not an audience. not a user base. a structural position through which one hop reaches the operational reality of an entire end-customer economy.

that is what the position is worth. if the signal it generates is actually worth something.

which brings up the strongest objection to this entire thesis. chapter IV answers it.

next: IV. the telemetry layer →

CHAPTER IV

the telemetry layer

the main idea: MSPs are being consolidated hard. Shield by Thrive, funded by OpenAI in exchange for training rights on IT services data. Titan by General Catalyst, from a $1.5B fund half-earmarked for AI-driven services rollups. everyone reads it as level two automation. it is telemetry acquisition. and the pattern generalizes. Metropolis is a parking company that is actually a telemetry of urban movement. the most valuable companies of the next decade will be indistinguishable from telemetries of the economies they operate in. the software is the sensor. the panel is the product.

MSPs are being consolidated hard right now.

Shield Technology Partners is being rolled up inside Thrive Holdings, Joshua Kushner’s $10B+ vehicle. in december 2025, OpenAI took equity in Thrive Holdings. not cash for shares. OpenAI contributed its research and engineering teams and platform access in exchange for equity, and in the Shield-specific deal, the right to train its models on the platform’s IT services data.

read that transaction carefully. it is the tell.

OpenAI has a bridge to the enterprise problem. their models get better with real workflow data. and the largest concentration of unexploited enterprise workflow data in the world sits inside the SMB IT services layer. the layer that adopts AI last. the layer with no bespoke tooling. the layer that runs on tickets, spreadsheets, and phone calls.

OpenAI is not buying MSP margin. they are buying telemetry into every SMB that runs their IT through an MSP.

meanwhile, General Catalyst is doing the same play with different framing. in august 2025, GC led a $74M round in Titan, an AI-enabled MSP holding company, and Titan simultaneously acquired RFA, an MSP with over 400 financial services clients. the funding came from GC’s $1.5B creation fund. roughly half of that fund is earmarked for AI-driven consolidation in traditional services. legal. insurance. IT. BPO.

GC’s own investment memo on Titan is explicit. “real productivity transformation requires technologies to be embedded at the core of businesses, not just layered on top of existing systems.” they are targeting a 3x increase in net margins through AI-enabled service delivery.

so the surface argument for both plays is level two. buy MSPs. automate the manual work. capture the margin expansion.

that is not what the smart money is actually paying for.

the read that’s missing.

MSPs are the last delivery layer of AI into the 95% of the economy that will never adopt AI directly.

no small manufacturing firm is going to hire an AI transformation consultant. no regional accounting firm is going to build their own agent stack. no medical practice, no logistics broker, no distributor is going to install OpenAI’s platform through a corporate sales cycle. they are going to call their MSP.

and their MSP is going to install whatever their consolidated parent company tells them to install.

which means whoever owns the MSP layer owns AI adoption for SMB. not through better marketing. through the delivery pipe itself. the AI reaches the SMB through the MSP or it does not reach the SMB.

that is not a service margin play. it is a distribution position on the AI adoption curve.

the panel at scale.

every SMB an MSP serves generates operational data.

every ticket. every network event. every incident. every deployment. every user provisioned. every application installed. every security posture check. every backup event. every service call.

at one MSP that is noise. at 200 MSPs across a national market that is a real-time panel on SMB operations at a level no incumbent tech vendor holds.

which sectors are hiring. which sectors are laying off. which industries are getting hit by ransomware. which regions are scaling their infrastructure. which companies are consolidating and which are fragmenting. all of it visible before it appears in any published statistic. all of it visible at the platform layer, because the MSP contracts already grant data-processing rights to the parent.

OpenAI is training their models on this. that is the transaction Shield/Thrive already made. but the same panel has value to buyers OpenAI will never sell to. insurers underwriting cyber. banks underwriting SMB credit. private equity firms sourcing acquisitions. state agencies tracking SMB economic health. sovereign funds allocating capital. none of them have this data. none of them can get it any other way.

the tell inside the tell.

the operators most bullish on MSP consolidation are explicitly not optimizing for near-term profitability.

if MSP consolidation were about margin expansion, the smart operators would be maximizing free cash flow per acquired firm. they are not. they are maximizing coverage. maximizing telemetry surface area. maximizing the panel density that only exists once you cross a threshold of national coverage.

margin expansion is the story they tell the LPs. telemetry acquisition is the actual play.

so which is it. the transformation chapter I underwrites, or the telemetry this chapter describes?

both, in layers. transformation is the floor: real cash-flow improvement, the PE-downside argument, what every buyer underwrites. telemetry is the option written on top of the floor: what the sophisticated minority is positioning for. same transaction, two layers of value. and the option is the layer the multiple doesn’t price yet.

the pattern generalizes.

MSPs are one instance.

Metropolis is not a parking company. Metropolis is a real-time telemetry of urban movement. every vehicle in every Metropolis-operated lot generates data. entry time. dwell time. license plate. payment behavior. revisit frequency. seasonality. the parking business pays for the sensor grid. the telemetry is the asset.

a consolidated tax advisor network is not an accounting practice. it is a telemetry of the SMB economy. every entrepreneur’s cash flow, every industry-level margin trend, every regional employment shift, in near-real time.

a consolidated property manager is not a real estate services firm. it is a telemetry of residential real estate cash flow. every maintenance backlog, every rent behavior, every vacancy trend, every insurance claim.

a consolidated insurance broker network is not a placement business. it is a telemetry of SMB risk. every loss pattern, every premium adequacy signal, every structural shift in exposure.

the pattern is not accidental. it is what happens when a service operation crosses the density threshold at which its byproducts become more valuable than its outputs.

the inversion, sharpened.

chapter II named this. chapter IV proves it.

in level one and level two the software is the product. in level three the software is the sensor and the panel is the product.

the service operation still runs. the customers still get their tickets closed, their taxes filed, their properties managed, their policies placed. but the reason a sophisticated acquirer pays to consolidate the vertical is not the operation. it is the telemetry the operation happens to generate as a byproduct.

the most valuable companies of the next decade will be indistinguishable from telemetries of the economies they operate in. the operation is the delivery mechanism for the sensor. the sensor is the delivery mechanism for the panel.

what the layer actually captures.

be precise about what the platform records, because “telemetry” convinces no one and a data inventory convinces everyone. three strata, each with a different owner and a different buyer.

stratum one: engagement exhaust. who uses which feature, how often, on how many clients, with what latency. this is the diligence layer. the proof the network is real. it transfers with the network when the network sells: it is what “documented engagement” means in a data room. it also powers behavioral qualification. a node’s activity curve is the first succession marker.

stratum two: practice-level signals. staffing changes, client-count trajectories, engagement decay, owner age, feature-adoption depth. this is the seller-pipeline layer. the succession radar. it transfers only through the discoverable flag: owners who opted into being found are handed over as exactly that. what an owner confided outside the flag transfers to no buyer, ever.

stratum three: the meaning layer. the aggregated financial reality of the SMEs behind the nodes. cash cycles, margin trends, payment behavior, sector composition. classified by the layer that gives raw movement its meaning. this is the panel. its buyers are institutions, and its price is set by calibration length, not node count.

engagement proves. signals originate. meaning compounds. three strata, three buyers, one grid.

the density threshold.

not every service operation becomes telemetry. the threshold matters.

one tax advisor is not telemetry. 50 tax advisors is not telemetry. 1,500 tax advisors in a national market is telemetry. one MSP is not telemetry. 20 MSPs is not telemetry. 200 MSPs across a national market is telemetry.

this is why the smart acquirers are moving now. below the density threshold, the panel does not exist. above it, the panel appreciates. the window to build the position exists only in the transition.

Thrive, OpenAI, General Catalyst, and Titan are moving because they can see the threshold. everyone else is watching an MSP rollup and thinking about EBITDA multiples.

they are watching the wrong number.

the signal decay objection.

the signal exists. the delivery layer exists. the acquirers moving to build the position exist. but any specific data point from any specific panel decays fast. a “cyber losses are up in mid-market law firms” signal from january is stale by october. a “cash cycles are stretching in industrial distribution” signal from Q2 is priced in by Q4. the value of the panel is not the point value of any specific insight. it is something else.

the exclusivity question.

one shot left, and it decides the valuation.

the rothschild edge only works if the pigeons are exclusive. nathan got rich because he alone knew. if five families run courier networks, the edge prices in within the hour.

and the panel will not be the only sensor grid pointed at the SMB economy. five rivals already hold pieces of it. so the question that decides everything: what does the multiplier panel see that the others don’t?

take them one at a time.

the bank. sees its own book, not the market. no single institution holds a national SMB economy, and banks do not pool data with their competitors. worse, the bank sees movements without meaning. a €50k inflow could be revenue, a loan, or an owner’s deposit. the classification lives one layer up, with the bookkeeper. and most structurally, the bank is a counterparty. the owner negotiates against the bank. lines, rates, collateral. the pre-event signal is systematically withheld from it. the one sensor everyone assumes is closest to the money is the one the money actively hides from.

verdict: broad but blind. movements without meaning.

the payment processor. faster than everyone and narrower than everyone. real-time sight of the card-and-online fragment of revenue, in an SMB economy that runs on invoices and bank transfer. no cost side. no payroll. no P&L.

verdict: fast and shallow.

the payroll provider. proves the counter-case in a single dimension. ADP moves markets with one axis and decades of calibration. which makes it the strongest public evidence of what a full panel would be worth, and no argument that one exists.

verdict: one axis. proof of concept, not competition.

the labs’ agents. every AI agent inside an SMB is itself a sensor, owned by the lab, not by the panel. but the agents see how a company works, not what it earns, owes, and pays. workflow, not meaning. chapter V splits those layers precisely, because they decay at different speeds.

verdict: workflow without economics.

the answer in one line. everyone else sees movements. the multiplier layer sees meaning. classified, reconciled. and meaning plus calibration is the layer the next chapter shows is time-locked.

chapter V names the economics.

next: V. panel economics →

CHAPTER V

panel economics

the main idea: the objection: point data decays in weeks. official statistics catch up in months. why is a real-time SMB panel worth anything eighteen months later? because the value was never the archive. panels are priced by length and freshness together. one quarter of data is noise. five years plus this morning’s feed is a moat. this is how alternative data has always been priced.

now the objection.

the panel produces signals. signals decay. official statistics catch up. any specific “sector X is compressing” data point is worth a lot in july and worth nothing in eighteen months. so the argument that the panel appreciates while everything else in the stack depreciates seems to break the moment you take the temporal dimension seriously.

the objection is real. i’ve raised it myself against operators pitching data-play theses without understanding what they were actually building.

here is the answer. it is precise and it changes what you’re actually holding.

the value was never the archive.

an archive is a museum. a collection of dated facts nobody needs. the value is the freshest feed read against the longest calibration history.

point signals decay. panels don’t.

one quarter of SMB cash-cycle data is noise. you can’t distinguish seasonality from structural shift. you can’t build baselines. you can’t tune early indicators. you don’t know what a normal june looks like so you can’t spot an abnormal one.

five years of SMB cash-cycle data plus this morning’s feed is a different asset entirely. now you can calibrate. you can separate what always happens in june from what has never happened in june before. you can tune the sensitivity of your early indicators against actual downstream outcomes. you can build baselines that make new prints meaningful.

panels are valued by length and continuity, not by point values.

this is how alternative data has always been priced.

alternative data is any data source that sits outside traditional financial filings and public statistics. credit card panels, satellite imagery, app usage, geolocation, web scraping, payroll feeds. hedge funds and institutional investors pay for it because it shows economic reality before official numbers do. the industry has existed for two decades and prices every feed the same way.

without history there’s no backtest. without a backtest, nobody trusts the fresh print. this is not a philosophical claim. it is how the alternative data industry actually works and has worked for two decades.

ADP publishes the national employment report every month. it moves markets. every hedge fund with a macro exposure watches it. ADP’s data is not more accurate than the Bureau of Labor Statistics. it is fresher. and it can be trusted because ADP has run the panel for decades and has calibrated its signals against downstream BLS revisions thousands of times.

no fresh feed, no trust, no premium. no history, no backtest, no market.

ADP’s asset is not this month’s employment data. it is the calibration history that makes this month’s employment data readable.

Bloomberg knows this.

Bloomberg Terminal costs $30,000 per user per year. what a Bloomberg subscriber actually pays for is not the current price of every asset. every price is public. what they pay for is decades of aligned, calibrated, timestamped, corporate-action-adjusted history that lets them price relative to something coherent.

if Bloomberg lost all its history and kept only today’s prices, no fund would renew.

if Bloomberg lost today’s prices and kept twenty years of history, most funds would find another vendor within a quarter.

both are true. and both prove the same point. panels are the interaction of history and freshness. neither one alone.

Constellation proves it happens in verticals too.

in may 2026, Constellation Software acquired Keypoint Intelligence, the benchmark authority of the digital-imaging industry. Constellation did not buy Keypoint’s current data. they bought Keypoint’s decades of position as the calibration reference for a vertical.

every fact Keypoint produced in 2024 was stale by 2026. that was never the point. the point was that in 2026, when someone in the imaging industry wanted to know whether a new print was normal or abnormal, they compared it against Keypoint. the calibration position had accumulated. that is what Constellation paid for.

the same asset class applies to SMB panels. it just does not exist yet in most verticals. nobody has ADP for SMB tax filings. nobody has Bloomberg for property-management operations. nobody has Keypoint for MSP incident data. the panels that would make those markets legible do not exist. the multipliers that would generate them are being consolidated for the first time now.

the compounding math.

this is what makes it a level.

a competitor with unlimited capital cannot buy the years back. they can outspend on multipliers today. they can hire away the operators. they can lever up on acquisitions. they cannot replay 2026 through 2031 to build the calibration history the position requires.

this is what “time-locked” actually means. not “hard to build.” not “expensive to replicate.” mechanically impossible to compress. the tool depreciates because AI writes it. the operation replicates because a competitor imitates it. the panel appreciates because history only runs forward.

everything in the stack decays except the one thing that structurally cannot.

which means the position is available in a way it will not be in five years. the panel that exists in 2032 will be the one someone started building in 2026. calibration history compounds at the rate history passes. there is no shortcut.

and this is why the panel is the level.

everything below the panel in the stack has a substitute or a decay path. the tool substitutes to whatever an AI agent writes next quarter. the operation substitutes to a competitor with better capital. ownership captures more of the operation, but only while the operation itself remains defensible.

the panel has no substitute. a panel that started in 2026 is not the same asset as a panel that started in 2028. it never will be.

level three is not just a different object than level two. it is a different asset class entirely. one that appreciates with time. one that concentrates over time. one that in most verticals does not yet have a buyer because it does not yet exist to be bought.

what the telemetry cannot hear. yet.

be honest about what each layer actually sees, because the exclusivities decay at different speeds.

workflow exhaust, tickets, deployments, incidents, is already contested. the labs are buying it. that is what the Shield-class transactions are buying. assume zero exclusivity there within a few years.

meaning is different. the financial reality of an SME, the P&L behind the workflow, plus the calibration history that makes it readable. the labs’ agents see how a company works. they do not see what it earns, owes, and pays. and they cannot backfill the five winters of baselines that make a fresh number legible. meaning is the time-locked layer.

and above meaning sits intent. the advisor hears “i’m thinking about succession.” no telemetry hears that. today. but run the trendline forward honestly, because this document runs every other trendline forward: owners are beginning to tell their AI things they tell no human. the chat logs already contain intent at scale. today the labs’ agents see workflow, not the P&L. the trendline says the agent becomes the confidant.

so split the claim, because the two halves decay at different speeds. exclusivity on intent has a shorter half-life than exclusivity on meaning. the intent layer, who is ready to sell, when, at what price, is a wasting advantage: real now, decisive now, and to be banked now, while the trusted human is still the only one in the room. the durable position is meaning plus calibration.

meaning appreciates. intent burns.

the asset class is clear. the economics are clear. the time-lock is clear. what remains is the era claim, the timeline, and the falsifiable predictions that put this argument on a clock. chapter VI names them.

next: VI. the prediction economy →

CHAPTER VI

the prediction economy

the main idea: markets are won by anticipation: distribution built ahead of model capability, not behind it. when panels exist, vertical markets bifurcate into the sighted and the substrate.

extrapolating the trendline.

chapters I through V built the argument piece by piece. software became infrastructure. a third level of value extraction exists. multipliers generate it. the telemetry layer proves it. panel economics make it time-locked. now run the whole thing forward and name the era it produces.

in five years, every credible operator in a vertical will have the same automation. models commoditize. operations replicate. and over each vertical that passes the multiplier filter, a panel will exist: someone will hold the platform layer and watch that market’s economy move months before it moves on paper.

that is the prediction economy. not a product category. not a business model. an era in which the winners in vertical markets are no longer the ones who automate the work, but the ones who see the market through the work.

the anticipation trade.

the same logic that makes panels time-locked makes the window to build them time-locked too.

a panel that started recording in 2026 can never be caught by one that starts in 2028. that is the thesis. but it cuts both ways: the operator who sees this pattern first and builds distribution while the position is open is playing the only trade that matters. the operator who waits until the pattern is obvious finds the position already taken.

distribution built ahead of the consensus is the trade. the cleaning company filming hallways nobody photographs is playing it. the construction rollups betting on robotics before the robots exist are playing it. and whoever builds the first multiplier panel in a vertical is playing it.

the prediction economy is what the trade looks like when everyone can see it. by then, the position is closed.

that is not a fair fight.

in that world, competition looks like this. two acquirers in the same vertical, same capital, same AI stack. one pays €750 per introductory meeting to discover whether an owner might sell. the other has watched engagement, staffing, and cash behavior across the vertical for years, and sees, at pattern level, where the succession wave is forming, in an ownership base already past 55, before anyone has made a call.

same army sizes. that is not a fair fight, and it never becomes one. because the disadvantage isn’t capital, talent, or software. it’s years, and years cannot be purchased retroactively.

the sighted and the substrate.

vertical markets bifurcate into two kinds of players: the ones who see markets coming, and the ones who get seen coming.

the sighted originate at prices the blind can’t understand. funds with the feed price SME risk against banks reading statistics months stale. and the operators who spent the decade optimizing level-two margins without instrumenting the panel discover their true role in the story: they built the telescope, node by node, for someone else to look through.

and the position doesn’t just compound vertically. it replicates horizontally. a single vertical in a single market has a ceiling. but the same multiplier structure exists in every market with an SME economy and no incumbent panel. the position that works in one market works in ten. each one adding a geography to the panel. each one compounding the calibration.

the state is the last buyer.

every buyer named so far is private. run the era forward and the largest buyer class arrives last: the state.

states are blind at exactly the layer that decides their crises. a government’s sensor grid is its statistical apparatus, and it was built for accuracy, not speed: surveys, filings, revisions, publication lags measured in months. that was tolerable when economies moved at the speed of paper. it is not tolerable now. every recent crisis proved the same thing. when states subsidized their SME economies through the last shock, they subsidized blind: relief flowing into sectors nobody could see in real time, calibrated against numbers a quarter old, arriving late where it was needed and generously where it was not. the SMB layer, the majority of employment, the majority of firms, the layer where every downturn lands first, is precisely the layer the state sees worst.

this has already happened once. during covid, economists built a real-time economic tracker from private-sector data, payroll processors, card spend, because official statistics were too slow for policy. the state’s blindness in crisis, and the private panel that filled it, is not a hypothesis. it is a documented precedent.

and the era this document describes makes that blindness strictly more dangerous. extrapolate the trendline the whole thesis runs on: intelligence commoditizes, and the scarce input flips from thinking to seeing. that flip does not stop at the private sector’s edge. a state whose institutions reason with abundant intelligence over stale ground truth is not a smarter state. it is a faster-moving blind one. in the prediction economy, the gap between the sighted and the substrate is not only a gap between acquirers. it is a gap between jurisdictions. the economies that can see themselves in real time will allocate, respond, and stabilize against the ones reading last quarter’s paper.

the sight is being built either way. the only open variable is under whose law. chapter IV documented the tell: lab capital is already buying telemetry into the SMB layer, one consolidation at a time, under contracts the end customer never saw. the panels over national SME economies will exist, because the private buyers are already paying. so the sovereignty question is not whether. it is under whose architecture, whose jurisdiction, and whose law the sight over a nation’s own economy accrues. a sensor layer over a country’s small-business economy is critical infrastructure from the day it reaches density. whether or not anyone has called it that yet.

the US is where this gets built first. the largest SMB economy in the world, the deepest pool of multiplier verticals, the most active buyer class for vertical software, and the most capital stacked behind AI rollups. every condition this thesis requires is present at scale: fragmented multiplier layers across tax, insurance, property management, and MSPs. a buyer class (Constellation, Beacon, General Catalyst’s portfolio) already paying for the instruments. and a legal architecture, state-level and federal, that supports anonymized, aggregate data collection at the platform layer. the panel race starts where the capital, the buyers, and the multiplier density already sit.

the state’s own incumbent cannot build this. the statistical office is the incumbent argument at state scale: it holds the mandate and cannot spend it. built for accuracy and delay, bound to methods that make its numbers comparable across decades, it cannot retrofit real-time, platform-layer collection any more than a member-owned cooperative can monetize its members’ clients. which is why the state arrives in this thesis the way every actor arrives in this thesis: as a buyer. central banks already purchase nowcasting feeds in fragments. payroll data here, scanner prices there. nobody has sold them the SMB economy itself, because it has never existed to be sold.

and the precaution, stated once, because it is the strongest form of the argument: the next crisis is not a hypothesis, only its date is. a state that cannot see its own SMB economy in real time will, when it comes, subsidize blind again, and will buy the sight afterward, at panic prices, from whoever built it. the choice available now is narrow and real: whether the panel a federal institution eventually procures was built under defensible architecture, by builders whose methods it can audit and endorse, or bought, late, from a source it cannot verify.

one honest cost, named because this document names its costs: infrastructure important enough for a state to buy is important enough for a state to want oversight of. that is not a reason to avoid the buyer. it is a reason the architecture was written before node one.

the bet, priced.

every thesis is a position, and a thesis that won’t name its bet can’t be priced. so name it: long the multiplier layer persisting through the build decade. the band from chapter I, AI transforms the workflow, the multiplier stays, is what this entire structure stands on.

now price it honestly. the band does not hold still. every model release moves it upward, and somewhere past 2030 the legally reserved tasks, the signature only a licensed advisor can give, the placement only a broker can make, may be the last wall standing. regulatory walls are real. permission is a true moat. they are also exactly what gets renegotiated when the productivity gap becomes absurd. a chamber that can revoke a concession today can be reformed tomorrow, and retiring owners don’t stay to defend walls.

so the bet is not “does the layer persist.” the bet is “does the layer persist longer than the build takes.”

the squeeze.

and inside that bet sits a squeeze a careful reader will find anyway, so it belongs in the document: the panel ripens on the same clock the layer may wither. five years of calibration started in 2026 matures around 2031. the band slide is plausibly 2030. the asset becomes trustworthy at roughly the moment its scaffolding becomes negotiable.

here is why that is survivable: the panel watches the SME economy through the multiplier layer, not the multiplier layer itself. chapters IV and V made this argument. the consent belongs to the end customer, not the advisor. if the advisor layer thins after density is reached, the sensor keeps reading. the multiplier is the launch mechanism, not the habitat.

so the squeeze does not break the thesis. it prices it: density must be reached while the multiplier still mediates. reach it before the band slides, and the panel outlives its scaffolding. miss it, and there is no second launch. the second hand on the same clock.

the predictions.

a thesis that risks nothing predicts nothing. so here are commitments. dated, checkable, falsifiable.

prediction one. by the end of 2027, serial acquirers of vertical software close at least five further acquisitions of vertical information authorities. benchmark businesses, data authorities, signal products with paying subscribers. Keypoint and RealEstateAPI were the start of a pattern, not exceptions. if the pattern stops, chapter V overread two deals, and this thesis loses its strongest external evidence.

prediction two. by end of 2028, at least one vertical in the US economy has a live panel that institutional buyers, insurers, banks, or macro funds, are paying for as an alternative data feed. if no vertical produces a priced panel by then, the thesis that multiplier telemetry creates a sellable asset class is wrong, and the entire third level described in this document does not materialize at market scale.

prediction three. by 2030, at least one state institution, a central bank, a sovereign fund, or a federal agency, is purchasing a real-time SME panel as an input to economic policy, crisis allocation, or regulatory oversight. if the state never arrives as a buyer, the “critical infrastructure” argument in this chapter overstates the demand, and the panel’s ceiling is set by the private buyer class alone.

the closing.

the software was never the asset. the operation was never the endgame. sight is. and the window to build it is the short interval before everyone else realizes what the people buying hundreds of vertical companies a year have already figured out.

the sophisticated money is already moving. it’s buying the instruments, buying the audiences, paying by the meeting.

this concludes the thesis. what follows in part two is the vehicle testing whether the position is manufacturable rather than accidental.

next: download →

THE WHOLE DOCUMENT

download

next: about →

ABOUT

· Researcher & Operator

Distribution for AI rollups: which customer bases are worth buying, and why. This paper is the thesis underneath: who sees the market first, and what that is worth once AI makes everything else cheap. Research and advisory at dis-tribution.com; essays at writing.izdebska.com.

next: about →